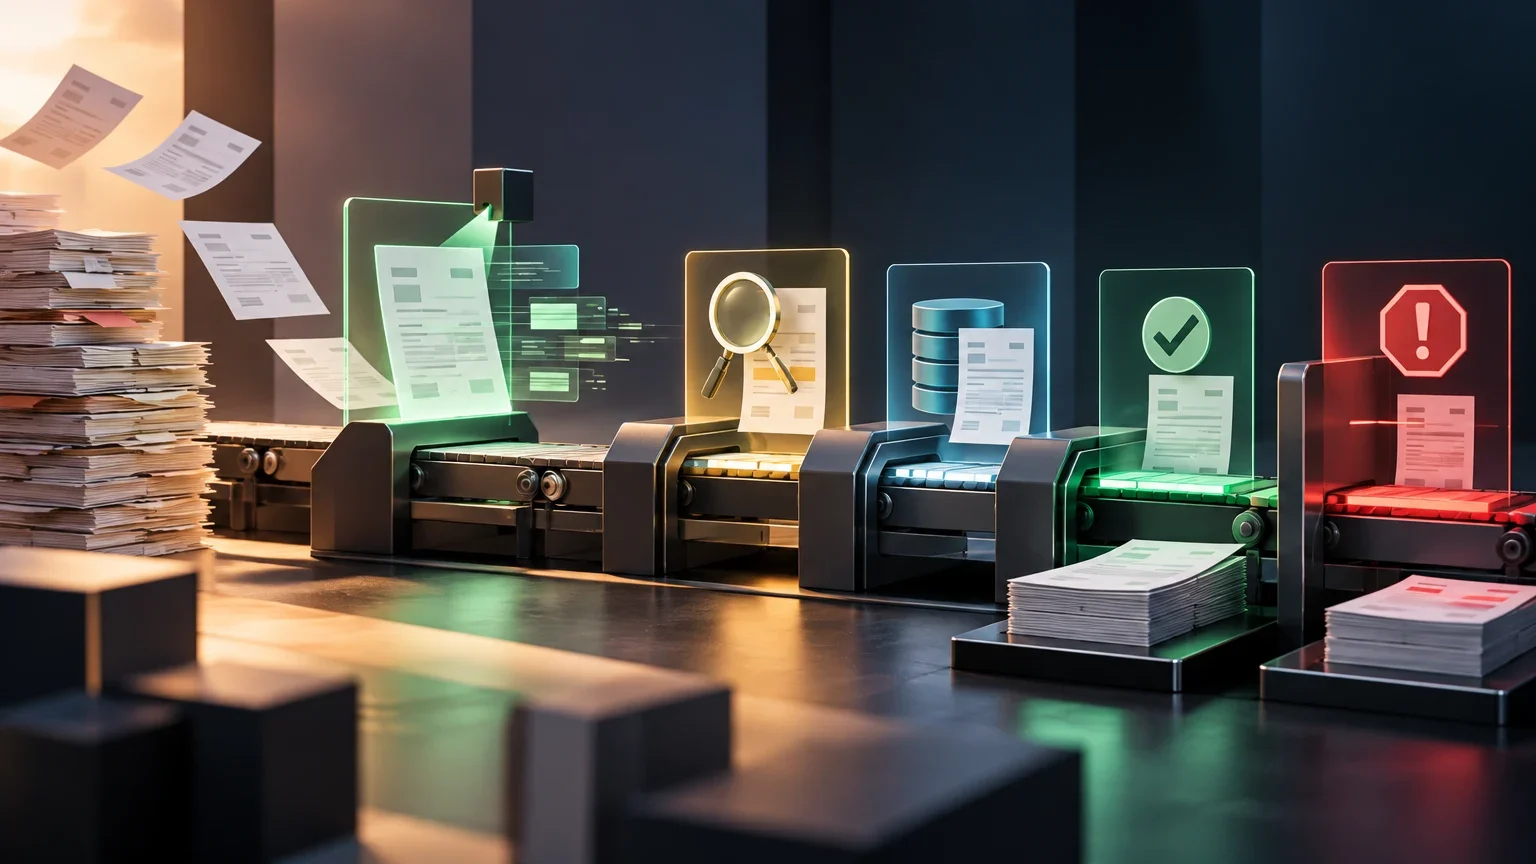
Start by defining the process and its decisions
Invoice processing combines distinct tasks: receiving a document, identifying its type, extracting fields, checking them against internal records, resolving discrepancies, recording the information, and approving it. Payment may belong to a later workflow and a different system. Before choosing technology, map the actual process and identify which person or system makes each decision.
This separation helps prevent a common design mistake: treating a document’s contents as proof that the underlying transaction is valid. An extraction tool may return an invoice number, supplier, or amount; that does not show that the goods were received, that the charge relates to an authorized purchase, or that it should be paid. Keep those decisions tied to your organization’s approved controls and records.
Define the scope of each stage, too. For example, the system might prepare a draft but not write to the ERP; it might suggest a match to a purchase order but not approve an exception; or it might record an invoice after deterministic validation and human approval. Make this boundary explicit before connecting automations to financial systems.
A minimal workflow map
For every step, record its input, output, owner, system involved, and permitted action. Keep receipt and extraction separate from validation, recording, approval, and payment.
- 01Receipt: retain the original document and assign a tracking identifier.
- 02Extraction and classification: produce structured fields and flag missing or uncertain values.
- 03Validation: compare fields with approved rules and authorized internal sources.
- 04Exception: stop progression and assign the case to a responsible person.
- 05Recording and approval: apply separate permissions and retain a record of who reviewed or authorized each change.
- 06Payment: keep it outside the scope of extraction; require the appropriate financial authorization workflow.
Separate extraction from validation
Extraction turns the invoice’s contents into usable data. This may include the invoice number and date, supplier, due date, subtotal, taxes, total, purchase order, and line items. Microsoft’s prebuilt model documents fields of this kind, confidence scores for its results, and specific file and format requirements. Those capabilities describe its extraction model; they do not prove that the data is correct against your company’s records or that an invoice is legitimate or payable.
Validation answers different questions: Is the supplier in the approved register? Does the purchase order match? Do the quantities agree with the receipt? Do the line-item and tax calculations add up to the total? Has an equivalent document already been received? Whenever possible, base these checks on deterministic rules and internal sources approved by your team. A model confidence score is a signal about its extraction, not accounting authorization.
Classification also needs a clear rule. Distinguishing an invoice from a credit note, receipt, or delivery note can determine which workflow applies. If classification is uncertain or the document contains several kinds of information, do not force it into an automatic route: retain the original and request a review. A technically plausible extraction is of little use if it is sent through the wrong process.
What each check establishes
Do not mix model predictions with business verification. Record the provenance of each result and the control that supports it.
| Task | What it produces or checks | What it does not establish on its own |
|---|---|---|
| OCR or AI extraction | Text and structured fields from the document | That a field is correct against the ERP or that payment is warranted |
| Format rule | Whether a date, identifier, or amount follows an expected format | Whether the data belongs to an authorized transaction |
| Internal matching | A match against recorded supplier, purchase order, or receipt data | That there is no fraud or undocumented business exception |
| Human approval | A decision by someone with defined authority | That prior checks were complete if no evidence has been recorded |
Choose a method for each stage, not by label
Conventional OCR may be sufficient when invoices are stable, fields appear in predictable positions, and the rules for checking them are straightforward. It can turn text in an image or PDF into machine-readable content, but the business still needs to confirm what each value means and what to do with it. Templates can work well for repeated formats, although they need attention when documents change or new suppliers appear.
AI assistance can help when layouts vary or contextual information needs to be classified and extracted. In that case, start by using it to propose structured results and send them to a review queue. Microsoft’s model documentation illustrates an extraction option with predefined fields, confidence scores, and input limits; it does not establish an overall accuracy rate that applies to every business. Measure performance on your own invoices, not against a generic promise.
Manual review preserves business context and may be the most sensible option for low volumes, exceptional documents, or high-impact decisions. It can also be combined with automation: a person reviews critical fields or discrepancies while the system handles repetitive, traceable tasks. The useful comparison is not “AI versus people,” but which combination minimizes errors and total cost at each stage.
Assess volume, variation, quality, and sensitive data
Count invoices by type, supplier, and channel; identify what proportion follows a pattern and which cases account for exceptions. Total volume is not enough: a large, heterogeneous set of documents may require more review than a smaller, repetitive one. Record formats, languages, scan quality, page counts, attachments, and recent template changes.
Check the documented limits of any service before designing the workflow. For example, Microsoft’s documentation specifies supported file types, sizes, and dimensions for its model, along with compatible languages and a PDF page limit. These are product characteristics, not a guarantee that your documents will be extracted without errors. If a document falls outside those limits or its quality makes critical fields unreadable, stop the automatic route.
Invoices may contain personal, tax, banking, and commercial data. Before sending documents to a service, check contractual and technical documentation to determine what data is processed, where it is processed, what permissions apply, how long it is retained, and how it is deleted. The available sources here do not establish those conditions for the solutions under consideration; verify them directly for the service, region, and configuration you plan to use. Restrict access and retain only what your organization’s applicable policies require.
Define controls and review levels
Classify fields by the consequences of an error. A typo in a description may create correction work; the wrong supplier, an incorrect total, or an altered bank account can have a greater financial impact. Scale review to that impact: check supplier identity, currency, amount, due date, banking details, and purchase-order references with particular care, in line with your internal controls.
Set explicit checks before recording: required fields; format and range; consistency among subtotal, taxes, discounts, and total; comparison with the purchase order and receipt where applicable; and duplicate detection. To detect duplicates, combine identifiers and context—for example, supplier, invoice number, date, and amount—and decide how to handle formatting differences. An automatic match should block or route the case for review, not delete or reject documents without a trace.
Do not use a single score to make decisions about the entire document. High confidence in the invoice number does not validate the total, and a clear extraction does not confirm that the service was received. Define thresholds by field and consequence, but calibrate them against reviewed data. If you cannot show that a rule works on representative cases, keep human review in place.
Decision matrix for early workflow stages
Use this as a starting point and adapt it to your organization’s permissions and risks. “Automate” here means prepare or validate within defined limits, not authorize payment.
| Observed condition | Recommended action | Required control |
|---|---|---|
| Legible document, known format, and complete non-critical fields | Prepare extraction for bounded automatic validation or sample-based review | Format rules, internal matching, and traceability |
| Low confidence or discrepancy in amount, supplier, or bank account | Stop progression and request human review | Confirmation against an authorized source and a recorded reason |
| Possible duplicate or no matching purchase order | Block automatic recording and route to the responsible person | Search using agreed keys and review the history |
| Unreadable or incomplete file, or one outside documented limits | Request a new copy or manual review | Retain the original, record the reason, and do not fill gaps by inference |
Set an autonomy boundary and an exception route
Decide what actions each component may take. A cautious sequence starts with reading and proposing, continues with a reviewable draft, and allows writing to a financial system only after rules, permissions, and recovery have been validated. Approval by a person with the appropriate authority should remain a distinct step whenever the process or policy requires it. Extraction alone must never trigger approval or payment.
Design an exception queue with useful categories: missing field, unrecognized supplier, amount discrepancy, possible duplicate, unmatched purchase order, unreadable document, or result outside accepted limits. Assign owners and deadlines, and define how a decision returns to the workflow without losing the original document. If someone corrects a field, retain both the proposed and corrected values and the reason, restricting access where appropriate.
Reversibility is part of the design, too. Before allowing writes, agree on how to undo an incorrect entry, who can do it, and which events must be audited. Test the integration account’s permissions: a tool intended to prepare drafts should not have unnecessary privileges to edit suppliers, change bank details, or initiate payments.
A controlled exception route
An exception is not a failed result to hide; it is an expected outcome of the process. Do not let incomplete data become a record that appears final.
- 01Stop the transition to the next stage and retain the original document.
- 02Assign a category and record which rule or data triggered the alert.
- 03Send the case to a person with appropriate permissions; do not request generic approval without naming an owner.
- 04Record the reviewed value, evidence consulted, decision, and reviewer’s identity.
- 05Resume the workflow only when the defined validations are satisfied; otherwise return or block the invoice with a documented reason.
Calculate the full operating cost
Compare the current process with the proposed alternative by cost per correctly accepted invoice, not merely per document processed. Include licensing or consumption, storage, email and ERP integration, implementation, rule maintenance, human review, exception handling, corrections, training, and oversight. If the system shifts work to another queue or increases coordination between teams, include that in the assessment.
Add the cost of failures and recovery. Correcting an entry may cost more than a preventive review; a duplicate that reaches payment may have different consequences from a misread descriptive field. Use your own time and error data to estimate scenarios, and identify which costs are measured and which are assumptions.
Feasibility also depends on integration and the ability to operate the workflow. Check that statuses do not diverge between the tool, accounting, and the ERP; that logs are available to reconstruct events; and that someone can maintain the rules when suppliers, formats, or internal requirements change. If you cannot sustain that work, reduce the scope before automating more stages.
Test representative documents against predefined criteria
Before deployment, prepare a sample that reflects frequent and infrequent suppliers, different layouts, scanned and digital documents, invoices with multiple line items, possible duplicates, missing fields, and known discrepancies. Protect the data and use a set whose provenance and permissions are clear. Have people annotate reference results using a consistent procedure; without that reference, you cannot measure whether an extraction matches the document or whether a validation works.
Evaluate results by field and invoice type: supplier, number, date, currency, subtotal, taxes, total, and line-item accuracy; the proportion routed for review; false alerts and undetected errors; resolution time; and outcomes of checks against internal records. Decide before testing which failures require you to stop. Aggregate metrics can hide errors concentrated in one supplier or a critical field.
Test operational failures as well: unreadable files, unexpected formats, temporary ERP outages, near-duplicate documents, retries, and insufficient permissions. Confirm that the workflow does not record incomplete data as final and that reversal works. Start in reviewable output mode without initiating payments. Expand autonomy only after results have been reviewed and a change in scope formally approved.
Pre-deployment test plan
Agreeing on criteria before reviewing results reduces the risk of retroactively justifying an automation that does not meet the required controls.
- 01Define the invoice sample and document which cases it includes and excludes.
- 02Create a human-reviewed reference set and record the applicable validation rules.
- 03Run the process without writing to financial systems and compare each field with the reference.
- 04Classify errors by severity, field, supplier, and source; measure review volume and time as well as accuracy.
- 05Approve, change, or stop the pilot based on agreed thresholds; retain evidence and the configuration version.
- 06Repeat the evaluation when the model, rules, integration, or document types change.
Set stop conditions and monitor the process
Stop automation when there is not enough evidence to validate a critical value, the document is unreadable or incomplete, a discrepancy remains unresolved, an untested supplier or format appears, a possible duplicate is detected, or the connected system returns an unexpected status. Also stop after repeated failures, permission changes, synchronization issues, or when the exception rate exceeds the team’s review capacity.
Define who can resume the workflow and what evidence is required. Do not let an automatic retry turn an uncertain response into a duplicate operation. For reversal, record what changed, restore the appropriate state in the relevant system, and check for downstream effects. If there is no tested recovery procedure, limit the integration to producing drafts.
Track errors by field and severity, routed cases, resolution times, corrections, detected duplicates, and format changes. Review rules and test samples on a defined schedule and after any significant change. The goal is not to maximize the proportion processed automatically; it is to automate only what can be checked, explained, and safely corrected.
Open questions
- The Microsoft documentation provided describes its own extraction model but does not give a general error rate or demonstrate validation against internal records, approval, or payment.
- The available sources do not support an independent comparison of total cost, performance, or security for OCR, AI, and manual review in a specific organization.
- Permissions, retention, data location, and deletion depend on the service, contract, configuration, and market; verify them directly before processing real invoices.
Keep exploring
Sources consulted
Corrections and transparency
If you spot incorrect or outdated information, send us a correction with the page and source we should review.
Submit a correction